NZDUSD
NZDUSD Correlation: Which Pairs Move With the Kiwi, and How to Avoid Doubling Your Risk
NZDUSD moves most closely with GBPUSD, EURUSD and AUDUSD, and most strongly against USDCHF and USDCAD. On ECB reference rates to October 23, 2026, its daily returns had a 0.74 correlation with GBPUSD, 0.72 with EURUSD and 0.66 with AUDUSD over three months, and -0.70 with both USDCHF and USDCAD. Over one year, AUDUSD was the closest twin at 0.80.
This guide turns those readings into decisions: which pairs repeat your NZDUSD trade, which ones offset it, how much risk you really carry when you hold two of them, and how to size each leg. The figures use the same data and windows as the free SIWAI AUDUSD vs NZDUSD correlation page, so you can check the current reading before you trade.
What moves NZDUSD
NZDUSD is the price of one New Zealand dollar (the kiwi) in US dollars. Two forces drive it. The first is the US dollar itself: when the dollar weakens against everything, NZDUSD rises together with EURUSD, GBPUSD and AUDUSD, and USDCHF, USDCAD and USDJPY fall. That shared dollar leg is why the correlation coefficient between NZDUSD and the other dollar pairs is usually strong.
The second force is New Zealand. The Reserve Bank of New Zealand sets the Official Cash Rate (OCR) eight times a year, and its past monetary policy decisions page shows it raised the OCR from 2.25% to 2.5% on July 8, 2026 and to 2.75% on September 2, 2026. New Zealand is also a large exporter of goods, tracked by Stats NZ imports and exports, and many traders watch the Global Dairy Trade auction results for that reason. A day driven by any of these is a kiwi day, and on kiwi days NZDUSD moves on its own.
A coefficient of +1 means the daily moves always line up, 0 means no linear link and -1 means they always move in opposite directions. Over the last three months, NZDUSD and AUDUSD closed in the same direction on 49 of 66 ECB fixing days (74%), and NZDUSD and USDCHF moved in opposite directions on 45 of 66 (68%).
NZDUSD correlation table: every major pair
The inputs are ECB euro reference rates (see the ECB reference rates page) loaded through the Frankfurter exchange rate API, converted to dollar pairs and compared as daily percentage returns. All windows end on October 23, 2026.
| NZDUSD vs | 1 month | 3 months | 6 months | 1 year |
|---|---|---|---|---|
| AUDUSD | 0.68 | 0.66 | 0.73 | 0.80 |
| GBPUSD | 0.78 | 0.74 | 0.71 | 0.74 |
| EURUSD | 0.71 | 0.72 | 0.73 | 0.75 |
| NZDJPY | 0.63 | 0.38 | 0.56 | 0.56 |
| USDJPY | -0.37 | -0.40 | -0.37 | -0.43 |
| AUDNZD | -0.14 | -0.50 | -0.53 | -0.37 |
| USDCAD | -0.66 | -0.70 | -0.64 | -0.65 |
| USDCHF | -0.55 | -0.70 | -0.70 | -0.74 |
How to read it in practice:
- Above about 0.7: a long in the other pair largely repeats your NZDUSD long. That is GBPUSD and EURUSD on every window, and AUDUSD on six months and one year. Check them on the GBPUSD vs NZDUSD and EURUSD vs NZDUSD pages.
- Below about -0.7: a long in the other pair mostly offsets your NZDUSD long, and a short repeats it. That is USDCHF and USDCAD over three months. See NZDUSD vs USDCHF and NZDUSD vs USDCAD.
- Between about -0.4 and 0.4: treat the pairs as mostly separate markets. USDJPY sits near that edge at -0.40 over three months (see NZDUSD vs USDJPY), because the yen has strong drivers of its own.
Is AUDUSD still the closest pair to NZDUSD?
Over one year, yes: 0.80, the highest reading in the table. Australia and New Zealand are neighbors with commodity linked currencies, and the AUDUSD vs EURUSD comparison found NZDUSD was AUDUSD's closest major too. But over the last three months, GBPUSD (0.74) and EURUSD (0.72) were both closer to NZDUSD than AUDUSD (0.66). Recent NZDUSD trading has followed the broad dollar more than the Aussie.
The AUDNZD row says the same thing from another angle. AUDNZD rises when the Aussie beats the kiwi. Its -0.50 reading over three months means that when NZDUSD rose, the Aussie often rose less, so the gap between the two currencies did a lot of the moving.
| NZDUSD | |
|---|---|
| ECB based rate, Oct 23, 2026 | 0.5687 |
| Change over 3 months (from 0.5786 on Jul 23) | -1.71% |
| Change over 1 year (from 0.5743 on Oct 23, 2025) | -0.98% |
| Typical daily move, 3 months (standard deviation) | 0.44% |
| Average fix to fix move, 3 months | 19.6 pips (median 13.8, largest 67.5) |
| Average fix to fix move, 1 year | 22.6 pips (median 18.2, largest 134.8) |
| Pip value of 1.0 lot (100,000 units) | $10 |
When the NZDUSD and AUDUSD link weakens
Sampled about once a month on rolling three month windows, the NZDUSD and AUDUSD correlation stayed between 0.83 and 0.87 from January to June 2026, then slid to 0.66 by October 20.
| Rolling 3 month window ending | NZDUSD vs AUDUSD |
|---|---|
| Jan 23, 2026 | 0.83 |
| Mar 24, 2026 | 0.87 |
| Jun 24, 2026 | 0.85 |
| Jul 23, 2026 | 0.79 |
| Sep 21, 2026 | 0.72 |
| Oct 20, 2026 | 0.66 |
The slide began in the same months as the two RBNZ hikes in July and September. That timing does not prove the cause, but it fits the pattern: the link tends to weaken when one country has its own story (a central bank move, local data, export prices) and strengthen when the US dollar is the story, such as on US inflation, jobs or Federal Reserve FOMC days. The largest NZDUSD fix to fix move of the year, 134.8 pips between April 7 and April 8, 2026, came on the same day as EURUSD's largest move, a clear dollar day.
How much risk you stack with two kiwi trades
Say you hold NZDUSD and one other pair, each sized to risk 1% of your account. If both stops are hit you lose 2%, whatever the correlation. What correlation changes is how often the two win and lose together. For two equal positions, the combined swing grows with the square root of 2 + 2 × correlation, in units of one position's risk:
| Second trade next to a NZDUSD long | Correlation of the two positions | Combined swing of 1% + 1% |
|---|---|---|
| Long AUDUSD (3 months) | 0.66 | about 1.82% |
| Short USDCHF (3 months) | 0.70 | about 1.84% |
| Long GBPUSD (3 months) | 0.74 | about 1.87% |
| Long AUDUSD (rolling high, Mar 2026) | 0.87 | about 1.93% |
| Long USDCHF (3 months) | -0.70 | about 0.77% |
A NZDUSD long next to a GBPUSD long, or next to a USDCHF short, behaves close to one 2% dollar bet. Buying NZDUSD and USDCHF together does the opposite: the two mostly cancel, so you pay two spreads for a small net position. The rule of thumb: one view, one risk budget. The guide to using currency correlation in forex explains the same math with more pairs.
Sizing NZDUSD from one risk budget
The US dollar is the quote currency, so NZDUSD pays $10 per pip on 1.0 lot, $1 on 0.10 lot and $0.10 on 0.01 lot, whatever the rate. The formula is lots = risk money ÷ (stop in pips × $10). Here are lots at 1% risk, with a 20 pip stop (close to the 19.6 pip average daily move) and a 40 pip stop:
| Account | 1% risk | 20 pip stop | 40 pip stop |
|---|---|---|---|
| $1,000 | $10 | 0.05 lot ($10) | 0.02 lot ($8) |
| $5,000 | $50 | 0.25 lot ($50) | 0.12 lot ($48) |
| $10,000 | $100 | 0.50 lot ($100) | 0.25 lot ($100) |
| $25,000 | $250 | 1.25 lots ($250) | 0.62 lot ($248) |
Now the two pair case. With a $10,000 account and one 1% budget of $100, a NZDUSD long with a 25 pip stop and an AUDUSD long with a 30 pip stop:
| Plan | NZDUSD (25 pip stop) | AUDUSD (30 pip stop) | Total at risk |
|---|---|---|---|
| Full 1% on each | 0.40 lot ($100) | 0.33 lot ($99) | $199 |
| One 1% budget, split 50/50 | 0.20 lot ($50) | 0.16 lot ($48) | $98 |
| Only the cleaner chart | 0.40 lot ($100) | none | $100 |
Lots are rounded down to the 0.01 step, so the dollar risk never goes above plan. Run your own numbers in the NZDUSD lot size calculator or the position size calculator. For accounts that are not in dollars, see how to calculate lot size in forex.
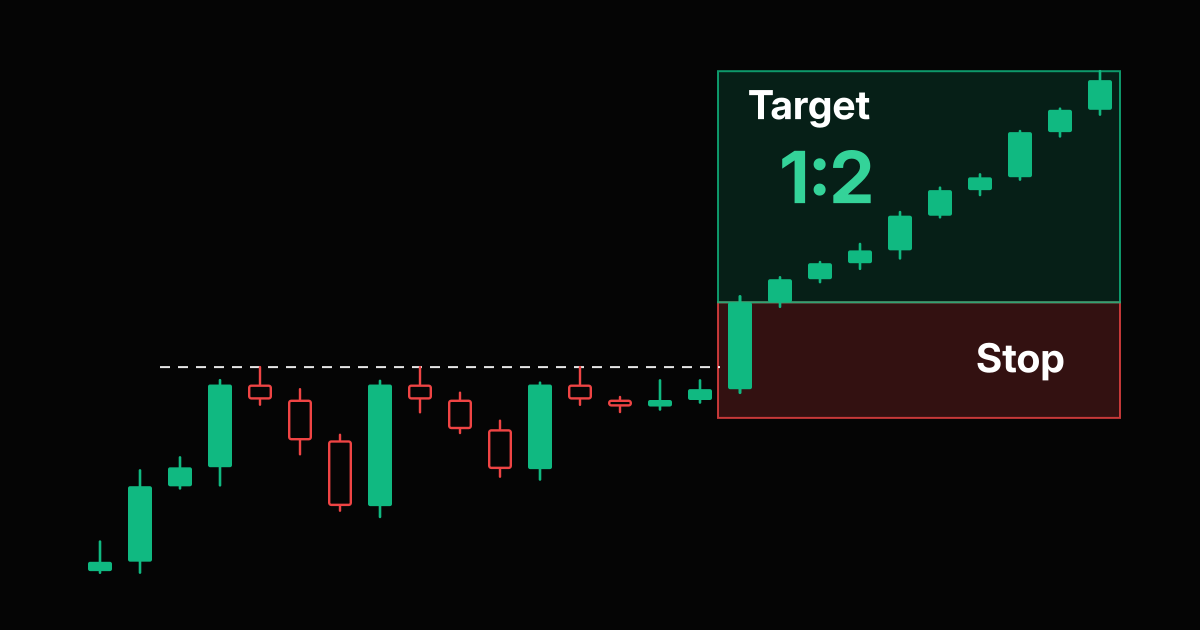
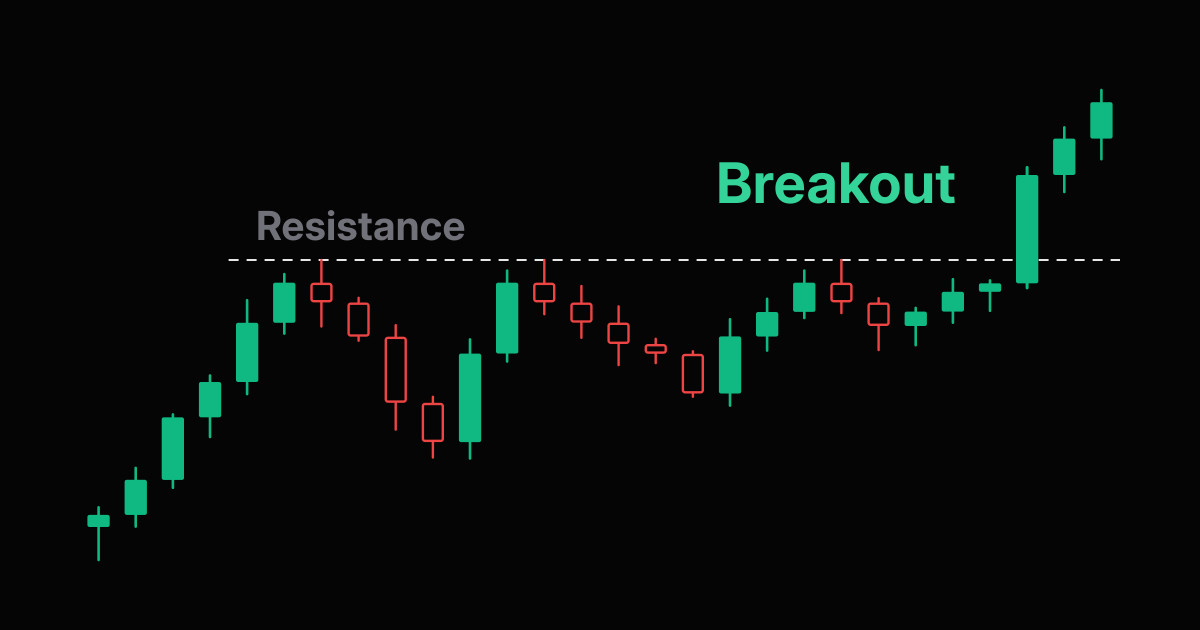
Using correlation to read a NZDUSD breakout
When NZDUSD closes above a clear resistance line, look at AUDUSD, EURUSD and USDCHF on the same timeframe before you buy:
- EURUSD and AUDUSD breaking out, USDCHF breaking down: it is a dollar move. You have one idea on several charts, so pick the cleanest one or split one risk budget.
- Only NZDUSD moving: it is a kiwi move, often around an RBNZ decision or New Zealand data. It can be a good trade, but the other charts will not confirm or hedge it.
- AUDNZD falling hard at the same time: the kiwi is outperforming the Aussie, so AUDUSD is the weaker way to express the same view.
None of this makes a breakout more likely to work. It tells you what you are actually betting on. Check the payoff with the risk reward calculator before you size, and see how oil changes a neighboring dollar pair in our USDCAD and oil correlation article.
A five step NZDUSD correlation check
- Open the forex correlation matrix and read NZDUSD on the 1M and 3M tabs, not only 1Y.
- List every open trade with a reading above 0.7 or below -0.7 against NZDUSD.
- Decide whether your idea is about the US dollar or about New Zealand.
- If it is a dollar idea, give all the related trades one risk budget and split it.
- Size each leg from its own stop at $10 per pip per 1.0 lot, and check the RBNZ calendar before holding through a decision.
Frequently Asked Questions
What pairs are correlated with NZDUSD?
On ECB reference rates to October 23, 2026, NZDUSD moved most with GBPUSD (0.74), EURUSD (0.72) and AUDUSD (0.66) over three months, and most against USDCHF and USDCAD (both -0.70). Over one year, AUDUSD was the closest at 0.80.
Is NZDUSD positively correlated with AUDUSD?
Yes. The correlation of daily returns was 0.68 over one month, 0.66 over three months, 0.73 over six months and 0.80 over one year to October 23, 2026. On rolling three month windows it was 0.83 to 0.87 from January to June 2026 and 0.66 by October 20.
Which pair is negatively correlated with NZDUSD?
USDCHF and USDCAD, at -0.70 each over three months to October 23, 2026, because the US dollar is the base currency in those pairs. USDJPY is weaker at -0.40. A long in USDCHF mostly offsets a NZDUSD long, while a short repeats it.
Why does the NZDUSD and AUDUSD correlation change?
Each pair also carries its own currency. RBNZ decisions, New Zealand data and export prices move the kiwi alone, and Australian news moves the Aussie alone. The rolling correlation slid from 0.85 in June to 0.66 in October 2026, the same months the RBNZ raised its OCR to 2.5% and then 2.75%.
Can I trade NZDUSD and AUDUSD at the same time?
You can, but if both express the same US dollar view, give them one risk budget and split it. At a 0.66 correlation, two trades risking 1% each swing like about 1.82% of risk, and if both stops are hit you still lose 2%.
What is the pip value of NZDUSD?
The US dollar is the quote currency, so 1.0 lot (100,000 units) pays $10 per pip, 0.10 lot pays $1 and 0.01 lot pays $0.10. With a $10,000 account, 1% risk and a 20 pip stop, that is 0.50 lot.
Risk Disclaimer: Trading stocks, options, futures, forex, commodities, and cryptocurrencies involves substantial risk of loss and is not suitable for every investor. Past performance does not guarantee future results. This article is for educational purposes only and does not constitute financial advice. You should carefully consider your financial situation and risk tolerance before trading. Never trade with money you cannot afford to lose. Correlation readings change over time and are calculated from daily ECB reference rates, which can differ from your broker's prices.